

A heavy commercial truck without competitive finance behind it is just a very expensive paperweight on wheels. When you need to put another rig on the road, you want a straight answer on numbers, not three weeks of bank bureaucracy.
In New Zealand, truck finance funds up to 100% of the purchase price on new and used commercial trucks, trailers, and transport machinery. The truck itself serves as the loan security—no residential property or mortgage over your home is required. Qualifying comes down to four practical pillars: the asset, the entity, your cash flow numbers, and the commercial contract.
By comparing funding appetite across 20 bank and non-bank lenders, commercial advisors deliver indicative term sheets within 24–48 hours and settlement in as little as 72 hours.
Truck Finance Parameters at a Glance
Here's how commercial truck finance is structured in New Zealand. It's the same frame for an owner-operator buying a first Kenworth as for a fleet adding five Isuzu curtainsiders:
| Feature | Lending Guideline | Operational Context |
|---|---|---|
| Maximum Financing | Up to 100% of purchase price | Zero cash deposit options available for qualifying businesses and clean assets |
| Security Required | The truck itself | Asset-backed lending — no residential home or commercial property mortgages needed |
| Eligible Assets | New & used commercial trucks | Prime movers, tippers, curtainsiders, refrigerated units, flatdecks & box trucks |
| Purchase Channels | Dealer, private sale & auction | Finance trucks bought from commercial dealerships, Trade Me private sales, or Turners auctions |
| Indicative Term Sheet | 24–48 hours | Fast preliminary assessment and tailored term sheets across 20 lenders |
| Settlement Speed | From 72 hours | Rapid drawdown once loan documents and vendor invoices are accepted |
Photo: RDNE Stock project / Pexels
What Truck Finance in NZ Actually Covers
Truck finance is a dedicated category of asset and commercial vehicle finance. Unlike unsecured business overdrafts or a commercial property loan where your real estate is at risk, asset finance isolates the debt directly to the vehicle being acquired.
The asset carries its own security registration via a specific charge on the Personal Property Securities Register (PPSR). This means your family home, commercial premises, and other operational business assets remain completely safe from cross-collateralisation.
You can finance new vehicles direct from authorised franchises, used trucks from independent commercial dealerships, private sales between transport operators, or auction stock. Learn more about broad machinery funding on our asset finance page.
Commercial Truck Categories We Fund
Asset lenders in New Zealand finance virtually every classification of commercial vehicle on the road:
Heavy Haulage & Prime Movers (Class 5)
Linehaul tractor units, logging rigs, heavy freight combinations, and bulk transport prime movers.
Civil & Earthmoving Tippers
Aggregate tippers, 6x4 and 8x4 dump trucks, hook loaders, and site muck trucks for civil contracting.
Curtainsiders & Box Trucks
Metro distribution trucks, 2 to 4-axle freight bodies, tail-lift delivery vehicles, and logistics units.
Refrigerated & Food Transport
Temperature-controlled chillers, freezer bodies, and insulated food distribution trucks.
Flatdecks, Crane Trucks & Transporters
Hiab crane-mounted trucks, scaffolding flatdecks, machinery transport trailers, and vehicle recovery units.
Vocational & Specialist Municipal Units
Concrete agitators, hydro-excavation vacuum tankers, water trucks, and municipal service vehicles.
Hauling a digger rather than buying one? The machine on the back is funded through equipment finance, and civil plant has its own guide on construction equipment finance.
Truck Finance Anywhere in NZ: Your Postcode Isn't Part of the Deal
Short answer: it doesn't matter where in New Zealand the truck is based. The lender looks at the truck, the business, and the cash flow. Not the town on the rego papers.
We're based in Swanson, Auckland, and place truck finance nationwide. A tipper operator in Gore gets the same 20 lenders, the same 24–48 hour term sheet, and the same up to 100% funding as a linehaul fleet in Manukau. The only real difference is the coffee meeting becomes a phone call.
| Region | Including |
|---|---|
| Auckland & Northland | Auckland, North Shore, Manukau, Papakura, Pukekohe, Waiuku, Whangārei |
| Waikato & Coromandel | Hamilton, Cambridge, Te Awamutu, Huntly, Morrinsville, Matamata, Tokoroa, Thames, Paeroa |
| Bay of Plenty | Tauranga, Mount Maunganui, Te Puke, Katikati, Whakatāne, Ōpōtiki |
| Taranaki, Hawke’s Bay & Manawatū | New Plymouth, Stratford, Hāwera, Waitara, Ōpunake, Hastings, Havelock North, Waipukurau, Wairoa, Palmerston North, Feilding, Whanganui, Marton, Taihape, Levin |
| Wellington & Wairarapa | Wellington, Porirua, Upper Hutt, Paraparaumu, Masterton, Carterton, Greytown, Featherston |
| Nelson, Marlborough & West Coast | Nelson, Richmond, Motueka, Tākaka, Picton, Westport, Hokitika, Franz Josef |
| Canterbury | Christchurch, Rolleston, Kaiapoi, Kaikōura, Ashburton, Timaru, Temuka, Geraldine |
| Otago & Southland | Dunedin, Milton, Balclutha, Queenstown, Wānaka, Cromwell, Alexandra, Gore, Invercargill, Bluff, Te Anau |
Buying a truck from another region
Plenty of good used trucks sell a long way from where they'll work. A Christchurch operator buying a tipper off a Hamilton dealer is normal, and lenders are fine with it. They want three things sorted before settlement:
- A pre-purchase mechanical inspection, especially on a private sale
- A clear PPSR search, so you're not inheriting someone else's finance
- A dealer invoice or signed sale agreement the lender can pay against
Funds go straight to the vendor once terms are signed. Nobody needs to fly to Hamilton with a bank cheque in their back pocket.
Photo: Tara Winstead / Pexels
Deposit, Loan Size & Term: Why There's No Fixed Grid
Short answer: many facilities fund up to 100% of the truck's purchase price, so you do not necessarily need to tie up working capital in a cash deposit. (Yes, that really does mean $0 deposit. No, it does not mean the lender skips checking your ability to service the loan.)
There is no single published rate card or rigid loan ceiling in commercial finance. Every deal is priced off five key risk parameters:
- The truck's age, make, and condition — a five-year-old daily-driver prices differently to a brand-new Euro 6 build
- Whether you are GST-registered and how the purchase is structured (chattel mortgage vs finance lease)
- The term length you request, matching the vehicle’s realistic operational lifespan (typically 2 to 7 years)
- Bank versus non-bank lender appetite — different credit policy thresholds for the same asset
- Your business cash flow and financial ability to service the monthly repayment cleanly
Lenders love promising "flexible terms" in glossy brochures. So does every gym membership in January. The only figure that matters is what is written on an indicative term sheet tailored to your exact deal—which we deliver in 24–48 hours.
Photo: cottonbro studio / Pexels
What Qualifies You for Truck Finance in NZ
Every commercial asset lender reviews the same four components, weighted according to their credit mandate:
- The Asset: The truck's age, mileage, condition, and resale valuation — mainstream brands (Kenworth, Isuzu, Scania, Volvo, Fuso, Hino, DAF) are straightforward to price and secure.
- The Entity: New Zealand registered company, partnership, sole trader, or trust with valid ID for all directors and principal guarantors.
- The Numbers: Your business cash flow, recent bank statements, and trading track record showing capacity to service monthly repayments comfortably.
- The Use Case: The truck's role in generating commercial revenue — an owner-operator with a dedicated transport contract prices differently to a seasonal backup unit.
Make sure your company records are up to date on the Companies Register before submitting an application. How long you have been trading is not a rigid barrier: banks typically prefer 12 to 24 months of trading records, whereas non-bank transport specialists can underwrite newly incorporated owner-operators backed by confirmed freight contracts.
Photo: Gustavo Fring / Pexels
Bank or Non-Bank: Who Actually Says Yes
Having placed asset finance deals across New Zealand since 2017, here is the honest reality: when a mainstream bank declines a good truck deal, it is almost always a rigid policy issue rather than bad numbers. The truck is solid, the work is lined up, but the applicant simply does not fit a standardised checklist.
An advisor who only submits to one or two banks is not advising—they are acting as a referral desk for whoever pays the easiest commission. We maintain relationships across 20 banks and non-bank lenders (7 trading banks and 13 non-bank specialists) plus institutional funders. If a bank declines your truck purchase on policy, we place it with a transport lender that underwrites the asset and cash flow immediately.
AML Commercial is a licensed Financial Advice Provider (FSP 714331), and Kundan Singh is registered as FSP 512966.
Tax, GST Refund & Chattel Mortgage Structuring
Structuring your commercial truck loan correctly has significant cash flow benefits for GST-registered Kiwi businesses:
- Upfront 15% GST Refund: Under a Chattel Mortgage / Specific Security Agreement, you take ownership of the truck at purchase. This allows your accountant to claim the full 15% GST input credit back from Inland Revenue (ird.govt.nz) on your next GST filing.
- Lump-Sum Debt Reduction: Many operators apply their IRD GST refund directly into their loan within the first 3 to 6 months, reducing the principal balance and lowering monthly repayments.
- Interest & Depreciation Deductions: Loan interest charges and vehicle depreciation are generally tax-deductible operating expenses against your business income.
- Balloon Repayments: You can structure a balloon payment (residual) at the end of the term to keep monthly cash outflows lower during peak growth periods.
*Note: Tax treatment varies based on your business structure and accounting method. Always confirm specific deductibility with your chartered accountant.
Photo: Deane Bayas / Pexels
When Truck Finance Isn't the Right Call
We tell clients directly when a facility does not fit their situation:
- Buying for personal or domestic run-around use: Commercial truck finance is strictly asset finance for business, trade, and income-earning transport operations. Consumer car loans or dealer retail finance apply for personal vehicles.
- You actually require capital secured against real estate: If the truck is merely incidental and your primary goal is releasing equity from commercial or residential property, explore our property finance solutions instead.
- Severe unserviceable debt with no identifiable revenue: Lenders require verifiable proof of income to demonstrate serviceability. If the business cannot show positive trading numbers or confirmed forward contracts, the file must be structured before applying.
For independent guidance on funding Kiwi business growth, business.govt.nz is an authoritative resource.
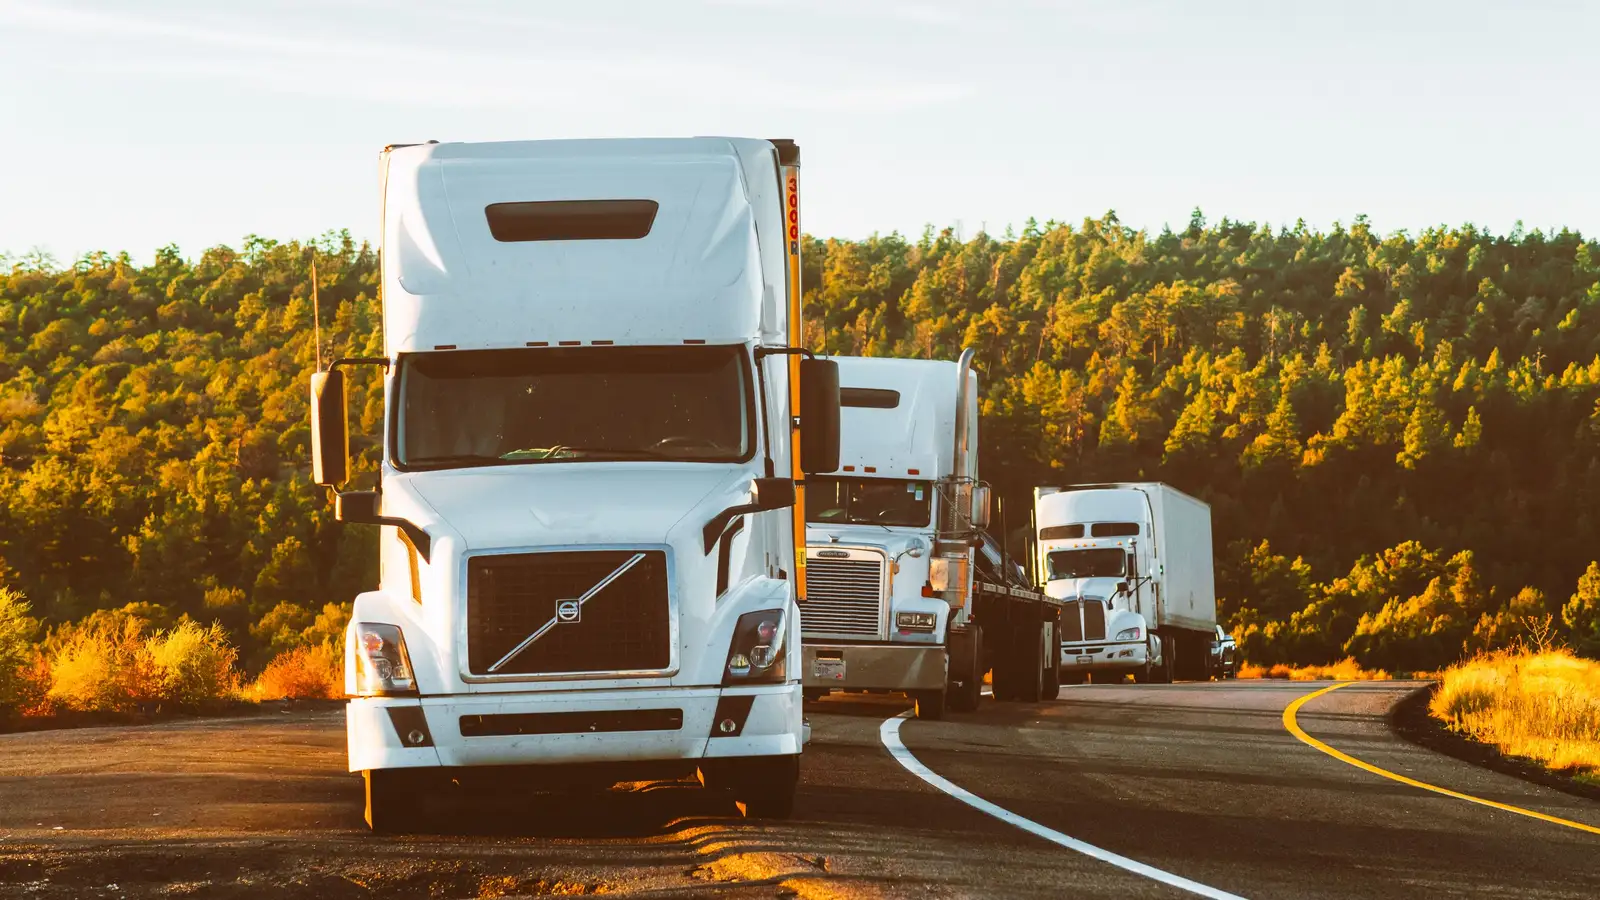
Photo: Quintin Gellar / Pexels
How to Apply and Get Funded
Three steps. Tell us the vehicle you want to buy (dealer quote, auction lot, or Trade Me listing) and provide your basic business entity details. We structure the facility and present it to the best-suited lender on panel.
Indicative term sheets are returned within 24–48 hours. Once accepted, supplier invoices are processed and funds are disbursed directly to the vendor in as little as 72 hours.
Start online through our simple asset finance application or call us directly on 0800 396 396 to discuss your transport fleet requirements.
Related Commercial Vehicle & Transport Finance Guides
Explore specialised transport financing guides across our advisory network:
- Log Truck Financing NZ: Heavy Forestry Rigs & Trailers
- Commercial Vehicle Finance NZ: Which Type Fits Your Business
- Ute Finance NZ: Commercial Ute Loans & Tax Deductions
- Van Finance NZ: Delivery & Trade Fleet Loans
- Equipment Finance NZ: Machinery & Plant Loans
- Food Truck Financing NZ: What Qualifies a New Operator